Wind Relief Offsets Hormuz-Driven Gas Spike
23.09.2026
Short term
Power — Short-term:
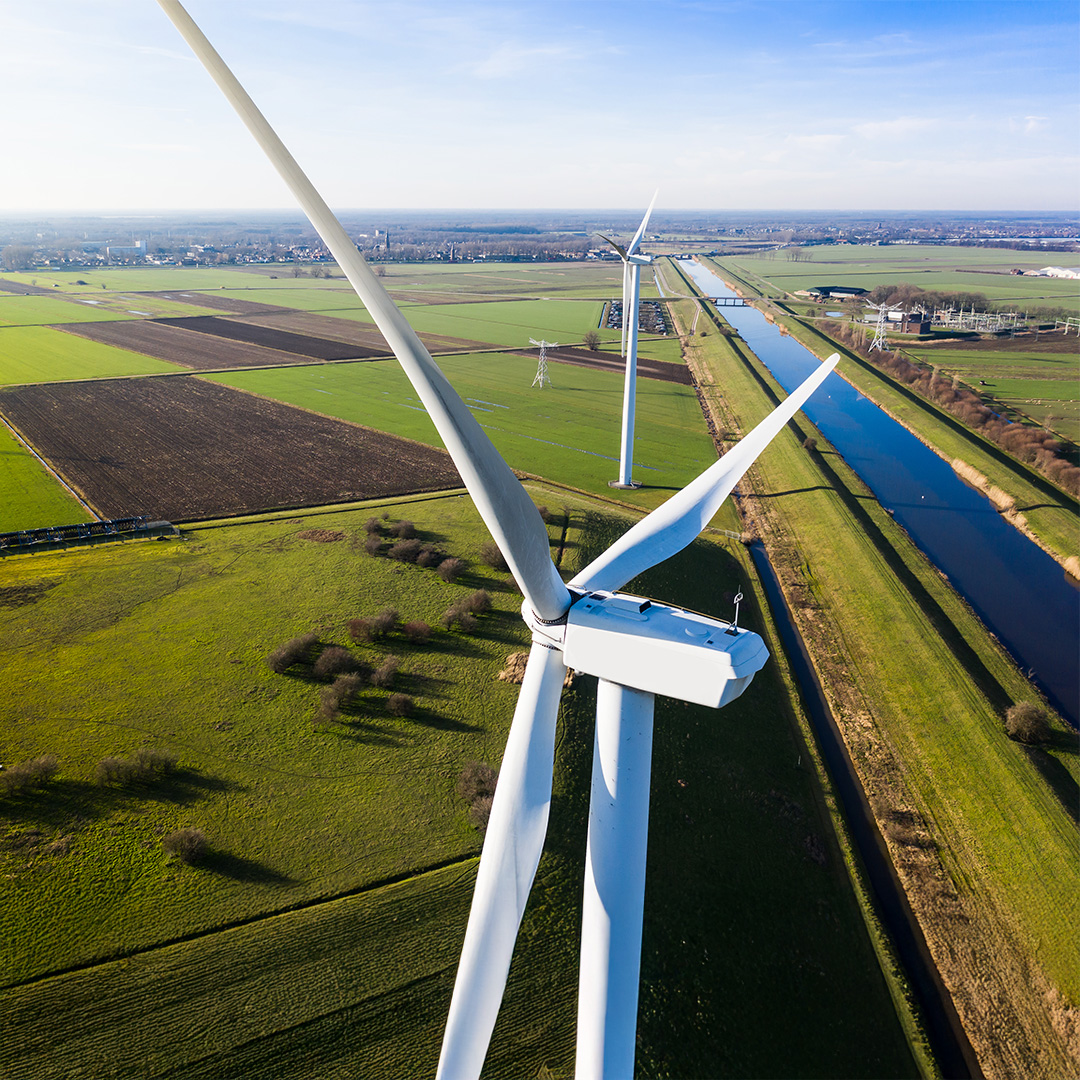
Dutch day-ahead baseload prices decreased in Week 38, averaging €139.1/MWh, down -€29.5/MWh week-on-week. The decrease was drive primarily by a sizable increase of wind energy in Netherlands and surrounding countries from Thursday to Sunday compared to the week prior. This heavily removed the need of more expensive assets such as gas plants to satisfy the merit order. At the start of the week however, the power prices were high due to lower volume of renewable energy, as well as TTF prices spiking due to the unresolved conflict between US and Iran, as well as EU sentiment worrying about gas shortages in winter. Here, the increase of TTF prices was making the required gas plants more expensive. Additionally, NL Rotterdam 1 and FLEVO 5 had ongoing maintance, reducing the possible production of gas plants.
Gas — Short-term:
TTF month-ahead prices rose in Week 38, averaging €80.1/MWh against €77.7/MWh in Week 37, an increase of €2.5/MWh. Prices spiked early in the week as escalating US-Iran tensions over the Strait of Hormuz pushed TTF above €80/MWh for the first time in roughly three years, before easing into the end of the week on hopes of diplomatic de-escalation. European storage remained a concern throughout, sitting at 68.49%, which is well below the five-year average of 84%.
Electricity (€/MWh)
Gas (€/MWh)
Long term
Forward curves moved independently of the spot gas rally this week. TTF was flat to slightly lower across the front of the curve. Here OCT-26 was unchanged at €79.5/MWh, Q1-27 down €0.7/MWh to €77.0/MWh. The back end firmed modestly, with CAL-27 up €0.2/MWh. Coal showed the same shape, softest at the front (OCT-26 −€1.3/MWh) and roughly flat further out. Power decoupled from gas: Base NL jumped €11.2/MWh in OCT-26 to €177.2/MWh despite flat TTF, then gave back €5.9/MWh in NOV-26, before posting modest gains through Q4-26 and Q1-27. One of the reasons of higher prices for OCT-26 is due to lower expected renewables for Netherlands and surrounding countries in this timeframe, compared to year(s) prior. As a result, CSS Base margins widened sharply in OCT-26 on the power move alone, narrowed again in NOV-26, and stayed under pressure from Q2-27 onward as power lagged a steadier gas curve further out.
Weekly changes
Base (€/MWh)
Peak (€/MWh)
Gas (€/MWh)
CO2 (€/MWh)
Aanmelden wekelijkse marktrapport
Vul hieronder uw gegevens in en ontvang gratis het wekelijkse marktrapport in uw mailbox.
Want to know more about us?
Contact us via our contact page or find out more about our company on the about us page.